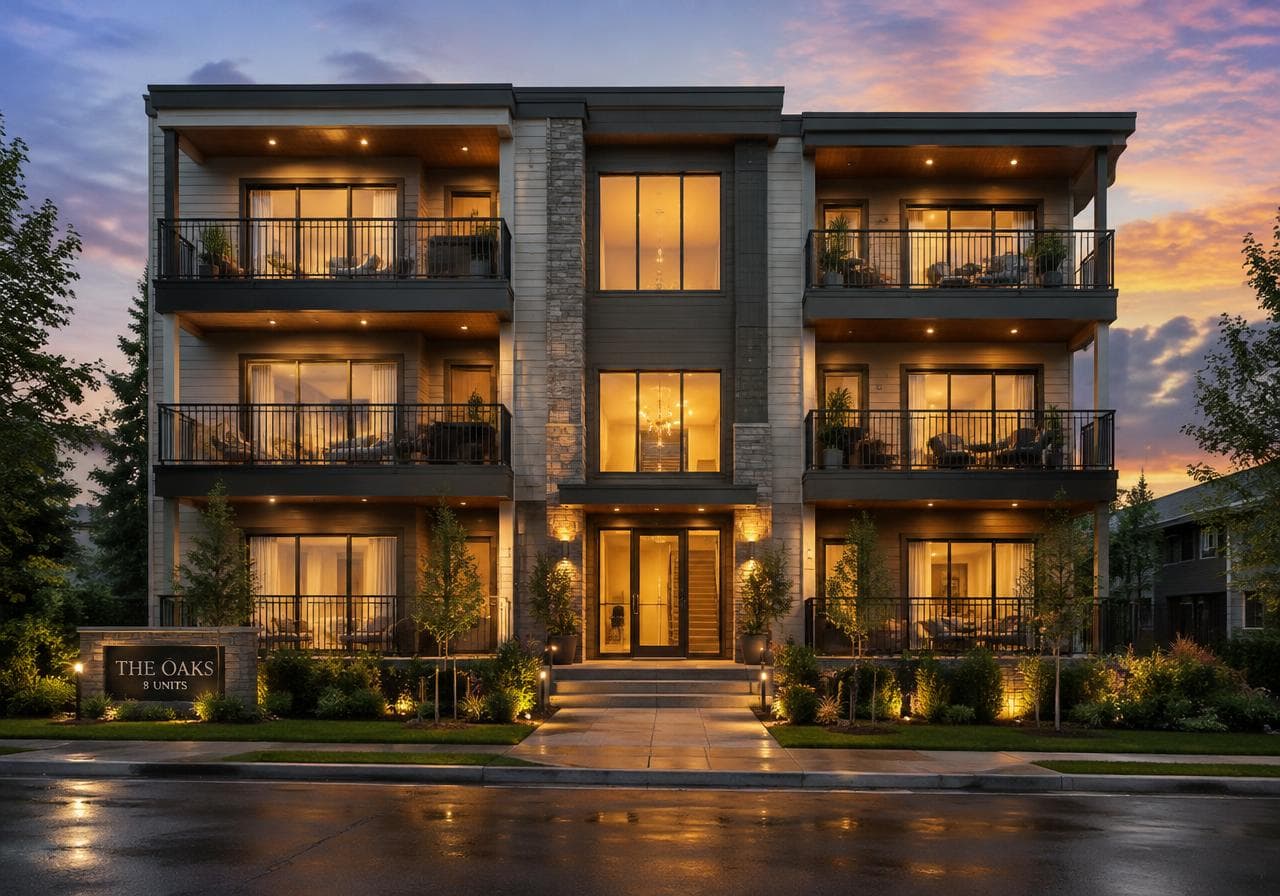
Once a building passes four units, conventional residential financing stops. Banks send you to commercial lending, which brings higher down payments, personal guarantees, longer timelines, and a pile of documents about your global financial position.
A DSCR loan for five to eight units keeps the process closer to a residential experience. The building's rent roll does the talking. You provide the property documents and entity paperwork, and the lender underwrites the income the building produces.
Who this loan fits
- Investors stepping up from fourplexes to small apartment buildings
- Owners with a stabilized building who want a long-term fixed loan
- Buyers who want to close inside a single-purpose LLC
- Operators who do not want a bank reading their entire tax history
What the lender reviews
For a building with several units, you should expect a rent roll listing every unit, its rent, and its lease status. Copies of the leases back it up. The appraiser will also report market rent, and the lender typically uses the more conservative figure.
Vacancy matters more as the unit count rises. A building that is mostly leased is a simple file. A building with several empty units can still qualify, but expect tighter loan-to-value and more reserves.
Why this range is different
Under five units, loans follow familiar residential rules. Above eight, the property is commercial and most programs change. The five to eight range gets its own treatment, and there are fewer lenders who do it well. That is a good reason to work with a specialist who does this every week.
Experience helps
Lenders are often more comfortable when the borrower has owned rentals before. If this is your first building of this size, tell us. There are ways to structure the deal and we will say plainly if a program is a stretch.
A sample six unit building
- Purchase price
- $780,000
- Loan amount (70% LTV)
- $546,000
- Total monthly rent (6 x $1,450)
- $8,700
- Principal, interest, taxes, insurance
- $6,540
- DSCR
- 1.33
Illustration only. Multifamily underwriting looks at actual leases, vacancy, and expenses, and terms vary by lender.